Once your flat's Minimum Occupation Period (MOP) is over, you may sell it on the open market and you may buy private property. Before that date you can do neither: HDB's rule for selling is "You must fulfil a set of eligibility conditions before you may sell your flat", and the MOP is one of them. For private property, HDB says: "Before you and your spouse can acquire private residential property, you have to fulfil the MOP of your flat."
The checklist below is what to find out before you list the flat or sign for the next home.
The checklist at a glance
| Item | What to find out | Where to check |
|---|---|---|
| Your MOP date | The date you may sell or buy private property | MyHDB Page, under My Flat > Purchased Flat > Flat Details and Minimum Occupation Period (MOP) |
| How the MOP is counted | Whether any period has been excluded, such as renting out the whole flat | HDB's selling eligibility page |
| Intent to Sell | Your eligibility to sell, the earliest date to grant an Option to Purchase, and the flat's EIP and SPR quota | My Flat Dashboard on the HDB Flat Portal |
| CPF refund | The CPF you used for the flat plus accrued interest, which goes back to your CPF account | CPF website, Home ownership dashboard |
| Outstanding loan | What is left on the flat's housing loan | MyHDB Page (Financial Info) for an HDB loan, or your bank |
| Private property after MOP | Whether you may buy, and whether you may keep the flat | HDB's acquiring private property page |
| Next home's loan limit | How much of the price a bank may lend, which is lower while the old flat's loan is still running | MAS Notice 645, worked out below |
| Order of selling and buying | Which comes first, and what each order costs | Sell the HDB first or buy the condo first? |
Your MOP date and how HDB counts it
HDB shows the date on your own account: "You can log in to MyHDB Page to check if you have met the MOP to sell your flat, under My Flat > Purchased Flat > Flat Details and Minimum Occupation Period (MOP)."
The length depends on the flat. For a flat bought from HDB or a resale flat bought on the open market, HDB lists "Unclassified/ Standard flats: 5 years" and "Plus and Prime flats: 10 years". A "Flat bought under the Fresh Start Housing Scheme" has an MOP of "20 years". DBSS and SERS replacement flats have their own terms on the same page.
HDB counts the period like this: "The MOP starts from the day your flat purchase is legally completed and excludes any period when you do not physically reside in the flat, e.g. when the whole flat is rented out with HDB's prior approval or when there has been an infringement of the flat lease." If you have rented out the whole flat at any point, your MOP date is later than five or ten years from completion, which is why the MyHDB Page date is the one to use.
Registering an Intent to Sell
The Intent to Sell is HDB's first step, done in My Flat Dashboard with Singpass. HDB states:
- "Upon registering an Intent to Sell, you will be informed of when you may start to grant an Option to Purchase (OTP) to potential flat buyers, which must be at least 7 days after registering the Intent to Sell."
- "Your Intent to Sell is valid for 12 months. It must be valid when you grant the OTP to the buyer(s) and when you submit the resale application."
- "There is no fee payable for registering an Intent to Sell."
- "You must register an Intent to Sell personally, regardless of whether you have engaged a salesperson."
Registering also gives you an estimate of your net proceeds, the EIP and SPR quota for your block, the upgrading status and recent transacted prices nearby. HDB adds that the result "is only an indication of your eligibility and does not constitute an approval by HDB to sell your flat."
The resale steps and HDB's waiting times
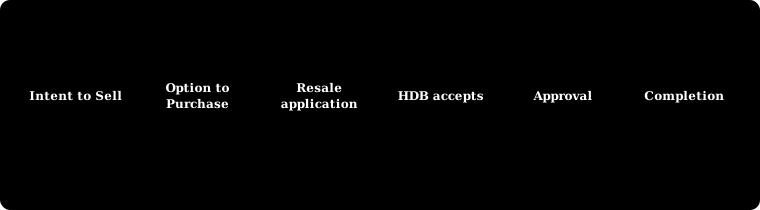
HDB sets out five steps: register an Intent to Sell, submit the resale application, endorse documents and pay fees, get resale approval, and attend the completion appointment. The waits HDB states at each point:
| Stage | What HDB says |
|---|---|
| Intent to Sell to Option to Purchase | The OTP can be granted "at least 7 days after registering the Intent to Sell" |
| Option period | "21 calendar days (including Saturdays, Sundays, and Public Holidays), from the date of granting the OTP" |
| Option Fee and Option Exercise Fee | Option Fee "Between $1 and $1,000"; Option Exercise Fee "An amount, which when including the Option Fee, will not exceed $5,000" |
| Resale application | Each side submits "Within 7 calendar days of each other's submission" |
| HDB's acceptance | "within 28 working days" of a complete application |
| Documents to endorse | "ready about 3 weeks after the application have been accepted" |
| Approval | "in 2 weeks' time after you and the buyers have endorsed the resale documents and made the necessary payments" |
| Completion | "about 8 weeks after HDB's acceptance of the resale application" |
| Cash proceeds | "credited directly to your bank account by the next working day after the sale of your flat is completed" |
| CPF refund | "within 7-14 working days from the date of the resale completion appointment" |
HDB also states that the completion date in its acceptance "is the earliest possible date to complete the transaction" and that it "is unable to accede to any request to bring forward the completion date".
Your CPF refund and outstanding loan
The cash you receive is the resale price less what the sale has to settle. HDB lists the deductions as the outstanding housing loan, the "Return of CPF savings used with accrued interest to your CPF account", the "Cash deposit received from your flat buyer (up to $5,000)", and "Any other amounts payable, e.g. resale levy, upgrading costs, etc."
CPF refund. CPF Board's rule: "In general, the amount you must refund is the principal you have withdrawn for your property (P) and the accrued interest (I), i.e. “P+I”. If you are age 55 or above and have pledged your property to set aside your retirement sum, you must also refund the pledged amount." CPF Board shows the exact figure in your Home ownership dashboard, "under the “What Happens If” section". The refund goes back to your CPF account, not to your bank account.
CPF Board also allows a voluntary housing refund before a sale. Its page says: "The earlier you refund your CPF savings, the less you'll need to refund upon the sale or transfer of the property."
Outstanding loan. HDB's rule: "The outstanding housing loan will be deducted from the resale price, if sufficient. If the resale price is insufficient to settle the outstanding housing loan, you must pay for the balance in cash." For an HDB loan, check MyHDB Page under "My Flat > Purchased Flat > Financial Info". For a bank loan, ask your bank.
Resale levy and upgrading costs. HDB: "A resale levy is payable in cash when you buy a second subsidised flat or an Executive Condominium unit from a property developer." It tells you whether this applies when you register the Intent to Sell. Upgrading costs billed while you still own the flat are also yours to pay.
Buying private property after the MOP
HDB's rule for when the MOP has to be met: it runs from the date you take possession of the flat to "Date on which the Option to Purchase (OTP) the private property is exercised" or "Date of the sale and purchase agreement of the private property, regardless of whether it is still under construction or ready for possession", whichever is earlier. So the MOP has to be complete on the day you exercise the OTP for the private home, not on the day you move in.
During the MOP, HDB says, "the flat owner, his/ her spouse and occupiers are not allowed to acquire private residential property. This includes exercising the Option to Purchase (OTP) or signing the sale and purchase agreement of the property, regardless of whether it is under construction or ready for possession."
After it: "After the MOP of the flat, there is no limit on the number of private properties which can be acquired."
Whether you may keep the flat depends on citizenship. For "Households with at least 1 Singapore Citizen flat owner", HDB says "The flat owner can retain the HDB flat if the owner, spouse, or occupier acquires the private residential property after the MOP." If all owners are Singapore Permanent Residents, "the SPR flat owners must sell the flat within 6 months of acquisition of completed/ uncompleted local private residential property", and they must notify HDB before the OTP is exercised.
If you buy before selling and the flat's loan is still running, the new home's loan counts as your second housing loan, with the lower limit shown below. The stamp duty IRAS charges when you own both, and when it refunds it, is set out in the selling-first or buying-first article.
If your next home is another HDB flat
HDB lets you own one flat at a time. Its resale terms set the deadline for the one you already own: "If they own any other HDB flat or residential property, the other flat or residential property must be disposed of within 6 months from the resale completion date. Any existing HDB approvals for the other flat to be rented out will also be revoked after 6 months from the resale completion date."
How much a bank lends for your next home
Your next home may be private, such as a condo or a landed house, or a bigger HDB flat. Most upgraders have one housing loan at a time: the old flat's loan is paid off from its sale before the new loan starts. The exception is buying before selling. For those months the old flat's loan is still running, and the bank counts the new loan as your second housing loan, which has a lower limit.
These are MAS's limits for bank loans, from MAS Notice 645, worked out with our rules script for a borrower aged 40 (figures checked 30 Oct 2026):
| When you take the new loan | Private home (condo or landed), 25-year loan | HDB flat, 25-year bank loan |
|---|---|---|
| The old flat is sold or its loan is fully paid off | 75%, at least 5% in cash | 75%, at least 5% in cash |
| You bought first and the old flat's loan is still outstanding | 45%, at least 25% in cash | 45%, at least 25% in cash |
| A longer first loan: over 30 years for a private home, over 25 years for an HDB flat, or running past age 65 | 55%, at least 10% in cash | 55%, at least 10% in cash |
The rest of the price is paid from your CPF and cash. If you take an HDB housing loan for an HDB flat instead of a bank loan, HDB sets its own limit; the table covers bank loans only.
The order of selling and buying
HDB asks sellers to "plan your next housing, before putting your current flat on the market for sale. Otherwise, your family may be left without a home." There are two orders, sell the flat first or buy the private home first, and they differ on stamp duty, the loan limit and where you live in between. The selling-first or buying-first article compares them with figures.
If you sell first and need more time in the flat, HDB allows a temporary extension of stay "for up to 3 months after the resale completion", only if you "Have committed to buy a completed property (can be another HDB flat or private residential property) in Singapore at the time of the resale application". The buyers have to agree to it. A new launch still under construction does not qualify, since it is not a completed property.
Questions owners ask
Can I sell my HDB flat before the MOP?
Not on the open market. HDB lists the MOP among the eligibility conditions for selling. For divorce, HDB says: "If the MOP has not been met, please write to us with your divorce documents."
Can I buy a new launch condo before my MOP ends?
No. HDB's rule covers private property "regardless of whether it is under construction or ready for possession", and it applies to the owner, spouse and occupiers.
Does renting out my whole flat affect the MOP?
Yes. HDB excludes "any period when you do not physically reside in the flat", and names a whole flat rented out with its approval as an example.
Which flats reach MOP in 2026?
HDB's pages give the rule, not a list by estate. Your own date is on MyHDB Page.
Is the CPF refund money I lose?
No. CPF Board's rule returns the principal and accrued interest to your own CPF account. It is not paid to you in cash, so it does not count towards the cash part of the next purchase.
Before you list the flat
The order you choose, and how much of the sale reaches your bank account as cash, decides how the next purchase is funded. If you would like these items worked out for your own flat, start a brief and we will go through them with you on a short call.
Rules checked against HDB, CPF Board and MAS on 30 Oct 2026. Rules and periods can change; HDB, CPF Board and MAS are the authorities on your own case.